English
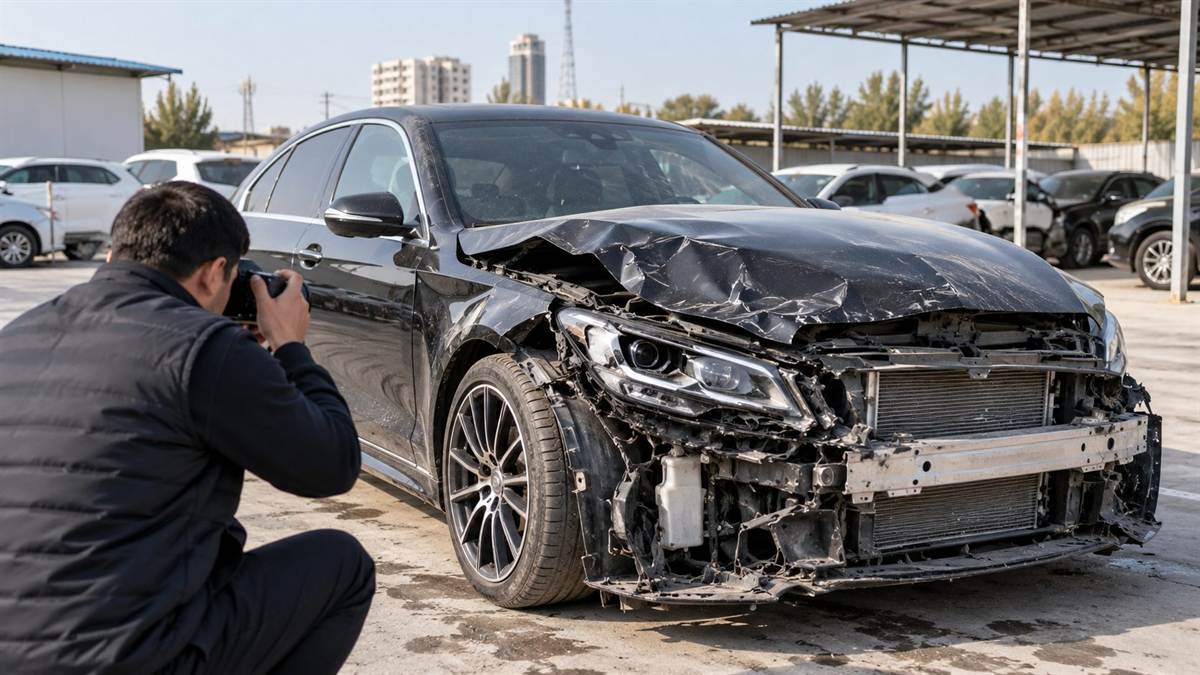
If your car disappears or becomes too expensive to repair after an accident, delaying the paperwork is the riskiest mistake.
Both claims begin with the same essentials: report the event to the competent authority, notify EUROASIA within 72 hours, preserve the evidence, and submit the complete document package.
First, check the programme shown in your policy. Theft is covered by LITE, SMART, and DELUXE. SIMPLE covers road traffic accidents only. You can review the differences in our KASKO programme comparison.
Three scenarios: what to know
Theft
Key test
Covered by the LITE, SMART, and DELUXE plans
First action
Notify the internal affairs authorities and call 1147 immediately
Total loss
Key test
Repairs equal or exceed the insured amount, or the vehicle cannot be restored
First action
Record the event and film the damage
Constructive total loss
Key test
Repairs are at least 75% of the vehicle’s actual value
First action
Preserve the documents and vehicle remains for assessment
The claims route at a glance
Event
Report it to the competent authority immediately
EUROASIA 1147 — without delay and within 72 hours
Video and documents → loss assessment
Decision within 5 working days after the complete package
Insurance act → payment within 5 working days
This does not mean the money will arrive exactly ten days after the event. The five-working-day decision period starts only when all required documents have been received. If criminal, administrative, or civil proceedings are underway, the insurer may postpone payment until the competent authority has issued its decision.
Scenario 1: your car was stolen
Under the KASKO offer, vehicle theft includes theft, robbery, armed robbery, and other unlawful taking of the insured vehicle. A vehicle that is not recovered is treated as a loss. If it is recovered with severe damage, the loss is assessed under the full-loss or constructive-total-loss criteria.
The first 72 hours
- Contact the internal affairs authorities immediately. The incident must be officially recorded. The claim file must include a certificate from the competent authority describing the circumstances.
- Notify EUROASIA on 1147. The offer requires notification without delay and no later than 72 hours after the event.
- Write down the instructions you receive. The car is no longer at the scene, so it cannot appear in an event video. Ask 1147 what to record in the app or by another method. Do not invent a substitute for the evidence the insurer requires.
- Collect the documents. You will need the KASKO policy, the competent authority’s certificate, the vehicle registration certificate, proof of ownership or lawful use, and a loss calculation prepared by a licensed valuation organisation.
- Respond to additional requests. The insurer may request further documents to clarify the circumstances or the amount of loss.
Theft is not recognised as an insured event if the vehicle was left in a condition that facilitated the theft, including keys left in the ignition or unlocked doors. State accurately in the claim where the keys were and whether the doors were locked.
Scenario 2: the car is declared a total loss
Drivers often use “total loss” for several situations. The offer sets out two distinct tests:
- full loss: the repair cost equals or exceeds the insured sum, or the vehicle cannot be restored;
- constructive total loss: the repair cost is at least 75% of the vehicle’s actual value.
For example, if a car’s actual value is UZS 300 million and a licensed valuer estimates repairs at UZS 240 million, the ratio is 80%. That is above the 75% constructive-total-loss threshold. The final determination and payout amount are recorded in the insurance act.
What to do at the scene
- Call the competent authority. For a road traffic accident, the Road Safety Service records the event. For another type of event, contact the authority responsible for that incident.
- Record video before the scene changes. Use the EUROASIA app to capture the damaged vehicle, the scene, the cause of the damage, and visible traces in real time. If the app is unavailable, record digital video on a phone or camera.
- Call 1147. This notification must also be made without delay and within 72 hours.
- Make the vehicle available for inspection. If requested, present it immediately or at an agreed time. Keep the vehicle remains available for inspection as well.
- Submit the complete document package. It includes the policy, documents from the competent authority, a copy of the registration certificate, the licence of the person driving at the time, identity and driving-authority documents, the original report from a licensed valuer or a service station defect report, and the photos and video.
How the payout is calculated
For theft or loss of the vehicle, indemnity is paid for the actual loss, but it cannot exceed the insured sum stated in the policy.
“Full value” therefore does not automatically mean any current market price. The central figure is the insured sum in your policy.
If the vehicle was insured for less than its full value, the offer applies a proportional calculation:
Insurance indemnity = actual loss × (insured sum / actual value)
Suppose the vehicle’s actual value is UZS 300 million, the insured sum is UZS 240 million, and the actual loss is assessed at UZS 300 million:
300 million × (240 million / 300 million) = UZS 240 million
In this example, the payout is capped at the UZS 240 million insured sum. The exact amount depends on the assessment, supporting documents, and insurance act.
Who keeps the vehicle remains
Usable parts of a severely damaged vehicle may retain value. Through abandonment, the policyholder relinquishes rights to the vehicle remains in favour of the insurer. The remains are transferred together with the documents confirming the transfer of ownership.
This is a documented procedure, not a verbal arrangement. The transfer and indemnity amount must be recorded in the insurance documents. When damage reaches 75% or more, the offer provides for consent to transfer the vehicle to the insurer under an abandonment act.
Decision and payment timing
Once the complete document package has been received:
Stage | Deadline |
|---|---|
Notify the insurer From the event; notice should be given without delay | Within 72 hours |
Claim decision After the complete document package is received | 5 working days |
Insurance payment After the insurance act is issued | 5 working days |
Late-payment penalty If the payment deadline is missed | 0.2% per day, capped at 30% |
If payment is late, the offer provides for a penalty of 0.2% of the overdue amount for each day of delay, capped at 30% of the amount payable.
Reasons a claim may be declined
A claim may be declined if the event is outside the policy coverage or the offer conditions were breached. Key examples include:
- a car insured under SIMPLE is stolen, because SIMPLE does not cover theft;
- unlocked doors or keys left in the ignition facilitated the theft;
- the driver was intoxicated, refused a medical examination, or left the accident scene;
- the loss was caused deliberately or false information was submitted;
- the event is not supported by real-time photos and video and the required competent-authority documents;
- the damage resulted from speeding, running a red light, driving into oncoming traffic, or breaching railway-crossing rules;
- the vehicle was confiscated, requisitioned, or seized by decision of a public authority.
Key points
- Theft is covered by LITE, SMART, and DELUXE, but not by SIMPLE.
- Record the event with the competent authority and notify EUROASIA within 72 hours.
- Constructive total loss begins when repair costs reach at least 75% of the vehicle’s actual value.
- Indemnity is based on the actual loss and cannot exceed the insured sum in the policy.
- The five-working-day decision period starts after the complete document package is received.
- Abandonment means a documented transfer of rights to the vehicle remains to the insurer.
It is easier to check your programme and insured sum before an incident occurs. Review the KASKO terms and choose the programme that fits. If you have questions, call 1147.